What Is a Journal Entry? Examples for Beginners
A journal entry is the record of a single business transaction in the accounting system. Each entry lists the date, the accounts affected, the amount debited to one or more accounts, the matching amount credited to one or more other accounts, and a short description. In double-entry accounting, total debits...

A journal entry is the record of a single business transaction in the accounting system. Each entry lists the date, the accounts affected, the amount debited to one or more accounts, the matching amount credited to one or more other accounts, and a short description. In double-entry accounting, total debits must always equal total credits.
- 1. The Parts of a Journal Entry
- 2. The Debit and Credit Rules
- 3. How to Write a Journal Entry in 4 Steps
- 4. 10 Journal Entry Examples
- 4.1. 1. Owner invests cash in the business
- 4.2. 2. Buying equipment with cash
- 4.3. 3. Buying supplies on credit
- 4.4. 4. Paying the supplier
- 4.5. 5. Cash sale
- 4.6. 6. Sale on credit
- 4.7. 7. Customer pays an invoice
- 4.8. 8. Paying monthly rent
- 4.9. 9. Taking out a bank loan
- 4.10. 10. Recording depreciation (adjusting entry)
- 5. Simple vs. Compound Journal Entries
- 6. Where Journal Entries Go Next
- 7. Common Journal Entry Mistakes
- 8. Frequently Asked Questions
- 8.1. Do debits always go on the left?
- 8.2. Can a journal entry have more than one debit?
- 8.3. Do I need to make journal entries if I use accounting software?
- 8.4. How long should business records be kept?
- 9. The Bottom Line
- 9.1. Sources
Every number on a balance sheet or income statement starts life as a journal entry. Once you understand how entries work, the rest of bookkeeping—ledgers, trial balances and financial statements—becomes much easier to follow. This guide explains the rules and then walks through ten common examples.
The Parts of a Journal Entry
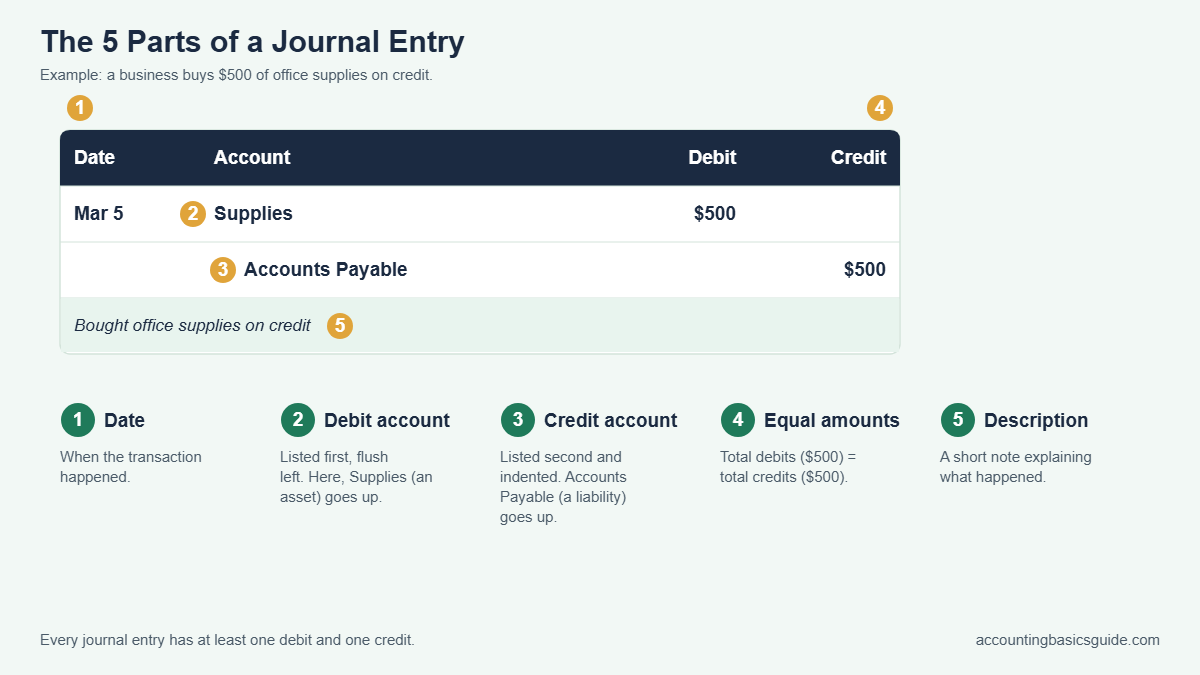
| Part | What it shows |
|---|---|
| Date | When the transaction happened |
| Account(s) debited | Listed first, with the amount in the Debit column |
| Account(s) credited | Listed next (often indented), with the amount in the Credit column |
| Description | A short note explaining the transaction |
| Reference | Invoice, receipt or check number, so the entry can be traced to a source document |
The Debit and Credit Rules
Debits and credits don’t mean “good” or “bad.” They simply mean left side and right side. Whether a debit increases or decreases an account depends on the type of account:
| Account type | Increase with | Decrease with | Normal balance |
|---|---|---|---|
| Assets (cash, accounts receivable, equipment) | Debit | Credit | Debit |
| Expenses (rent, wages, supplies) | Debit | Credit | Debit |
| Liabilities (accounts payable, loans) | Credit | Debit | Credit |
| Equity (owner’s capital, retained earnings) | Credit | Debit | Credit |
| Revenue (sales, service income) | Credit | Debit | Credit |
A simple way to remember it: the accounting equation is Assets = Liabilities + Equity. Accounts on the left side of the equation increase with debits; accounts on the right side increase with credits. Revenue increases equity, so it follows the credit side; expenses reduce equity, so they follow the debit side.
How to Write a Journal Entry in 4 Steps
- Identify the accounts involved. What changed? Cash, a bill owed, a sale?
- Decide whether each account increases or decreases.
- Apply the debit and credit rules from the table above.
- Check that total debits equal total credits, then add the date and a description.
10 Journal Entry Examples
The examples below use a small business with simple round numbers. Debits are listed first; credits are indented.
1. Owner invests cash in the business
| Account | Debit | Credit |
|---|---|---|
| Cash | $10,000 | |
| Owner’s Capital | $10,000 |
Cash (an asset) increases, so it is debited. Owner’s capital (equity) increases, so it is credited.
2. Buying equipment with cash
| Account | Debit | Credit |
|---|---|---|
| Equipment | $3,000 | |
| Cash | $3,000 |
One asset goes up and another goes down by the same amount.
3. Buying supplies on credit
| Account | Debit | Credit |
|---|---|---|
| Supplies | $500 | |
| Accounts Payable | $500 |
The business now owes the supplier, so accounts payable (a liability) increases. See what is accounts payable.
4. Paying the supplier
| Account | Debit | Credit |
|---|---|---|
| Accounts Payable | $500 | |
| Cash | $500 |
The liability is paid off, so accounts payable decreases (debit) and cash decreases (credit).
5. Cash sale
| Account | Debit | Credit |
|---|---|---|
| Cash | $1,200 | |
| Sales Revenue | $1,200 |
6. Sale on credit
| Account | Debit | Credit |
|---|---|---|
| Accounts Receivable | $2,000 | |
| Sales Revenue | $2,000 |
The customer owes you money, which is an asset. See is accounts receivable an asset.
7. Customer pays an invoice
| Account | Debit | Credit |
|---|---|---|
| Cash | $2,000 | |
| Accounts Receivable | $2,000 |
No new revenue is recorded here; it was already recorded when the sale was made.
8. Paying monthly rent
| Account | Debit | Credit |
|---|---|---|
| Rent Expense | $1,500 | |
| Cash | $1,500 |
9. Taking out a bank loan
| Account | Debit | Credit |
|---|---|---|
| Cash | $5,000 | |
| Loan Payable | $5,000 |
10. Recording depreciation (adjusting entry)
| Account | Debit | Credit |
|---|---|---|
| Depreciation Expense | $50 | |
| Accumulated Depreciation | $50 |
Adjusting entries like this are made at the end of a period. See adjusting journal entries.
Simple vs. Compound Journal Entries
A simple entry has one debit and one credit, like all of the examples above. A compound entry has more than two accounts. For example, if equipment costing $3,000 is bought with $1,000 cash and a $2,000 loan:
| Account | Debit | Credit |
|---|---|---|
| Equipment | $3,000 | |
| Cash | $1,000 | |
| Loan Payable | $2,000 |
Total debits ($3,000) still equal total credits ($3,000).
Where Journal Entries Go Next
Entries are first recorded in the journal in date order. They are then posted to individual accounts in the general ledger. At the end of a period, account balances are listed in a trial balance to confirm debits equal credits, and finally used to prepare financial statements. Most small businesses do all of this automatically in accounting software, but the logic underneath is the same.
Common Journal Entry Mistakes
- Debits and credits that don’t balance
- Recording revenue again when a customer pays an invoice that was already recorded
- Using the wrong account, such as recording a loan repayment entirely as an expense (only the interest is an expense)
- Missing descriptions or references, which make entries hard to check later
- Forgetting end-of-period adjusting entries
Frequently Asked Questions
Do debits always go on the left?
Yes. In a journal and in T-accounts, debits are recorded on the left and credits on the right.
Can a journal entry have more than one debit?
Yes. That is a compound entry. Total debits must still equal total credits.
Do I need to make journal entries if I use accounting software?
Software creates most entries automatically when you record invoices, bills and payments. You may still need manual entries for adjustments such as depreciation or accruals.
How long should business records be kept?
The IRS explains record-keeping periods in its guidance for small businesses. The right period depends on the type of record, so check the IRS recordkeeping page or ask a tax professional.
The Bottom Line
A journal entry records one transaction with matching debits and credits. Learn which accounts increase with debits (assets and expenses) and which increase with credits (liabilities, equity and revenue), always check that both sides balance, and you have the foundation for the rest of accounting.
This article is for general educational purposes only and is not accounting, tax or legal advice. For decisions about your business, consult a qualified accountant or tax professional.
Sources

Comments have been disabled.